- 1: Introduction
- 2: Estimated Cost List
- 2.1: Variable Costs
- 2.2: Fixed Costs
- 3: Target Profit
- 3.1: Target Profit and Units
- 3.1: Contribution
- 3.2: Selling Price and Sales Value
- 4: Analysis
- 4.1: Break Even
- 4.2: Margin of Safety
- 5: Marginal Costing Statement
- 6: Budget
- 6.1: Assumptions
- 6.2: Income and Expenditure Budget
- 7: Business Case
- 7.1: Analysis from perspective of break-even and margin of safety
- 7.2: Analysis from perspective of marginal costing
- 7.3: Analysis from perspective of budgeting
1: Introduction
This report will outline accounting for business in which launching a pop-up coffee stand at university campus will be the main area of focus. The elementary stages of this report will outline estimated cost lists as well as carry out a comprehensive evaluation of target profits likely to be achieved. The next stages of this report will focus on break-even and margin of safety analysis as well as provide a comprehensive income and expenditure budget for the venture. The final stages of this report will evaluate a comprehensive business case for the venture to determine overall feasibility likely to be achieved by undertaking this project.
Native Assignment Help offers academic guidance to students working on accounting assignments involving cost estimation, profit planning, break-even analysis and budgeting. As an Assignment Helper UK, we provide subject-focused support to help students understand accounting concepts, organise financial calculations and develop clear, well-structured reports that meet their university requirements.
2: Estimated Cost List
2.1: Variable Costs
The variable cost items estimated are raw material costs and utilities per coffee cup. The expected raw material cost per coffee cup is assumed as GBP 10 while the expected utility cost per coffee cup is expected to be GBP 5.
2.2: Fixed Costs
The fixed costs applicable for the pop-up coffee stand venture include rent, electricity, salaries and insurance. The cost estimated for rent and electricity is estimated to be GBP 3,000 and 6,000 respectively. Moreover, the estimated costs for salaries and insurance are identified as 7,500 and 1,500 respectively. The fixed costs assumed are totals for all three months and will be subject to equal distribution for each month.
3: Target Profit
3.1: Target Profit and Units
The estimated or expected target profit from the venture after three months is GBP 15,000 in which target profit for each month should ideally be GBP 5,000. The total expected units to be sold by the venture are 1000 per month.
3.1: Contribution
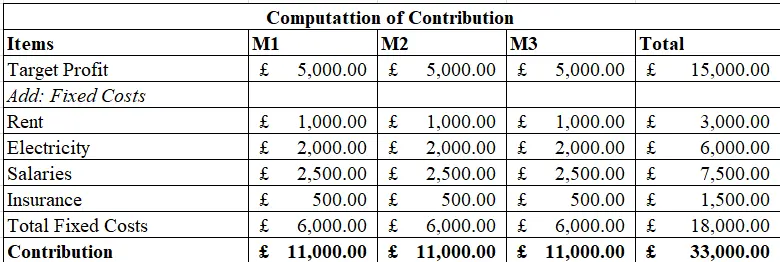
Figure 1: Contribution
According to the above figure, the contribution value for each month has been calculated as GBP 36,000 while the total combined contribution value has been measured as GBP 33,000. This figure has been achieved by adding anticipated fixed costs from expected target profit of GBP 5,000 per month and total expected target profit of GBP 15,000.
3.2: Selling Price and Sales Value
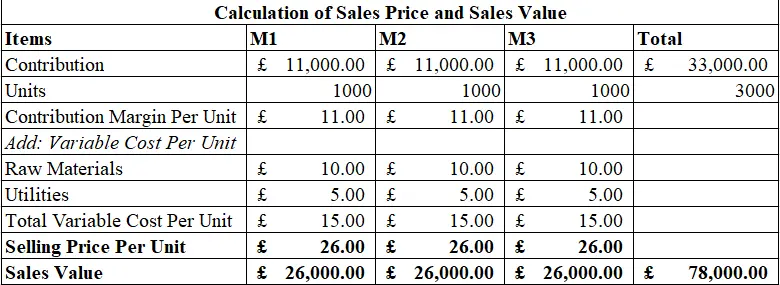
Figure 2: Sales Price and Sales Value
As per the above figure of computations, the selling price per coffee cup has been evaluated as GBP 26. The monthly sales value has been estimated as GBP 26,000 while the total combined sales value from 3 months of operations has been measured as GBP 78,000. In order to arrive at the selling price and sales value, total variable cost per unit of GBP 15 per coffee cup has been added with contribution margin per unit.
4: Analysis
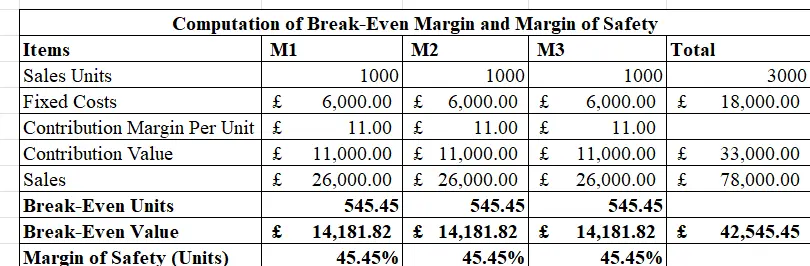
Figure 3: Computation of Break-Even and Margin of Safety
4.1: Break Even
According to the above figure, the break-even units for the new pop-up coffee stand venture has been calculated as 545.45 units. In order to calculate the break-even units, the formula applied is the division of contribution margin per unit to total fixed costs (Kolin et al. 2021). Similarly, the break-even value has been measured as GBP 14,181.82 for all three months while the total combined break-even value has been measured as GBP 42,545.45. Formula applicable for finding break-even value is the division of contribution value to the product of fixed costs and sales respectively.
4.2: Margin of Safety
Similarly, from figure 3 of calculations, the margin of safety for the new pop-up coffee stand has been calculated as 13.89% for all three months. Fatmawatie (2021), expressed and idealised that the margin of safety is identified as a critical strategic level for an organisation in which a company is expected to incur profits from productions and operations conducted. This is further formulated by dividing sales units from the difference between sales and break-even sales units.
5: Marginal Costing Statement
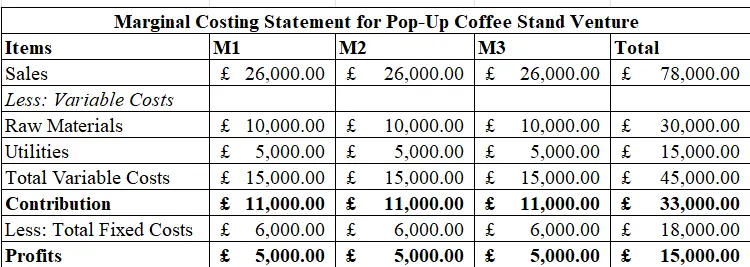
Figure 4: Marginal Costing Statement
According to figure 4 of the marginal costing statement, the monthly and total profits are measured as GBP 5,000 and 15,000 respectively. Hence, it can be established that sufficient profits are likely to be generated from the new venture of pop-up coffee stand at university campus. As per statements and expressions of Hosseini-Motlagh et al. (2022), a surplus profit from a venture is considered as a beneficial attribute for an organisation to emulate more profit seeking opportunities in the long run. The corresponding values of total variable costs from all three months has been measured as GBP 45,000 whereas the total sales value identified from all three months is measured as GBP 78,000. The marginal costing statement is also identified as a critical proforma which evaluates how operational reliability and stability is likely to be achieved by a company in future.
6: Budget
6.1: Assumptions
- An opening balance of GBP 14,000 as other income has been assumed for month 1.
- The incomes and expenses derived from the above marginal costing statement will be utilised to prepare the budget.
6.2: Income and Expenditure Budget
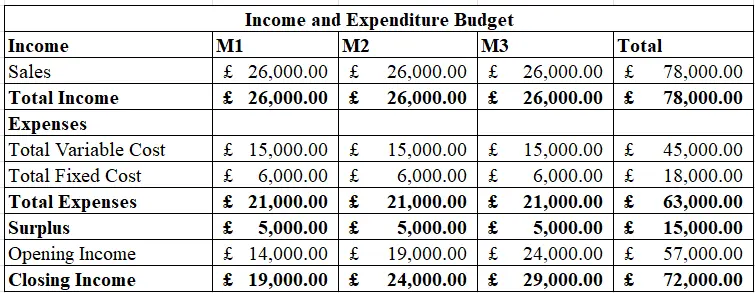
Figure 5: Income and Expenditure Budget
As per the above figure of income and expenditure budget, the surplus for M1, M2 and M3 has been measured as GBP 5,000 while the total surplus has been measured as GBP 15,000. The closing income for all three months is measured as GBP 19,000, 24,000 and 29,000 while the total closing income has been calculated as GBP 72,0000. Hence, it can be identified that a favourable closing income is expected to be incurred by undertaking the pop-coffee stand venture at university campus. Samanta et al. (2021), explained that a favourable closing income balance is beneficial for a company to ensure better future operational mobility and sustainability.
7: Business Case
7.1: Analysis from perspective of break-even and margin of safety
As per the break-even and margin of safety analysis conducted above, the levels are identified to be relatively higher and lower for both. In the estimated 1000 units intended to be sold, a total of 861.11 units are needed initially by the venture for equating costs and sales. As per critical opinions of Fadilah and Sidik (2023),a high portion of break-even for a venture can be a challenging aspect which can lead to hefty financial casualties if proper venture planning is not carried out. From the margin of safety perspective, a 13.89% figure denotes a break-neck situation for the venture where sudden cost escalations can lead to deteriorated project values and low sales. Overall, identifying ways to reduce costs are perhaps needed to be thought of by the new venture in order to increase margin of safety which in turn reduces burden of break-even sales units needed to be sold.
7.2: Analysis from perspective of marginal costing
From the above analysis of marginal costing statements, the total profits are estimated as GBP 15,000. This value is identified to be relatively sufficient for the new venture which allows ample scope to maximise future profits should more sales volume could be generated in future. The marginal costing analysis also elaborates the fact that a higher variable cost is available in comparison to fixed costs. As critically viewed by Alam et al. (2022), a higher variable cost proportion in comparison to fixed costs can possess operational challenges for a company due to which profit shrinkage could be experienced. Hence, the new venture should potentially identify how additional products can be accommodated in order to magnify a higher contribution margin that yields a low future break-even. Additional impetus could also be offered to consider how variable cost management can be initiated by the new venture if additional products cannot be accommodated in due course.
7.3: Analysis from perspective of budgeting
From the income and expenditure budgeting perspective, a higher closing income value has been established for all three months and for combined concerns. Therefore, the business case for the new venture is expected to reap beneficial returns in the short run provided all expected values at least meet equilibrium with actual performances. Alarussi and Gao (2021), stated and idealised that a high closing income and a high budgeting value for a venture is deemed beneficial to attain immediate project sustainability. Room for incorporating revenue maximisation and cost reduction should be considered for the future in order to magnify expected levels of closing and surplus income obtained. The increase in closing and surplus income for future should further enable the new venture to explore different potential university campus locations. A higher emphasis could also be provided to club or merge certain fixed or variable costs in the long run to stimulate a better operational control. Overall, the business case identified from all three perspectives are expected to fetch short-term beneficial rewards for the pop-up coffee stand venture to attain success.
Conclusion
This report has established that the new pop-up venture for coffee stand is expected to have a relatively higher break-even and a lower margin of safety. The analysis from budgeting indicates higher closing income expected to be incurred by the venture while the marginal costing statement indicates sufficient profits expected to be generated.
Reference List
Alam, M.F., Shtein, M., Barton, K. and Hoelzle, D.J., (2022), June. Sample efficient transfer in reinforcement learning for high variable cost environments with an inaccurate source reward model. In 2022 American Control Conference (ACC) (pp. 2892-2898). IEEE. Available at: https://ieeexplore.ieee.org/abstract/document/9867896 (Accessed: 5th June 2025)
Alarussi, A.S. and Gao, X., (2021). Determinants of profitability in Chinese companies. International Journal of Emerging Markets, 18(10), pp.4232-4251. Available at: https://www.emerald.com/insight/content/doi/10.1108/ijoem-04-2021-0539/full/html (Accessed: 5th June 2025)
Fadilah, A. and Sidik, S., (2023). Analysis of the Effect of Break Even Points and Margins of Safety on Profit Planning in Hospitality Companies Listed on the IDX 2017-2021. Eqien-Jurnal Ekonomi dan Bisnis, 12(03), pp.337-345. Available at: https://stiemuttaqien.ac.id/ojs/index.php/OJS/article/view/1502 (Accessed: 5th June 2025)
Fatmawatie, N., (2021). Implementation of break event point analysis and margin of safety in profit planning. Idarotuna: Journal of Administrative Science, 2(2), pp.132-146. Available at: https://doi.org/10.54471/idarotuna.v2i2.20 (Accessed: 5th June 2025)
Hosseini-Motlagh, S.M., Choi, T.M., Johari, M. and Nouri-Harzvili, M., (2022). A profit surplus distribution mechanism for supply chain coordination: An evolutionary game-theoretic analysis. European Journal of Operational Research, 301(2), pp.561-575. Available at: https://doi.org/10.1016/j.ejor.2021.10.059 (Accessed: 5th June 2025)
Kolin, D.A., Moverman, M.A., Menendez, M.E., Pagani, N.R., Puzzitiello, R.N. and Kavolus, J.J., (2021). A break-even analysis of tranexamic acid for prevention of periprosthetic joint infection following total hip and knee arthroplasty. Journal of Orthopaedics, 26, pp.54-57. Available at: https://www.sciencedirect.com/science/article/pii/S0972978X21001604 (Accessed: 5th June 2025)
Samanta, S., Ojha, A., Das, B. and Mondal, S.K., (2021). A profit maximisation solid transportation problem using genetic algorithm in fuzzy environment. Fuzzy Information and Engineering, 13(1), pp.40-57. Available at: https://ieeexplore.ieee.org/abstract/document/10479088 (Accessed: 5th June 2025)
Go Through the Best and FREE Samples Written by Our Academic Experts!
Native Assignment Help. (2026). Retrieved from:
https://www.nativeassignmenthelp.co.uk/accounting-for-business-individual-report-53115
Native Assignment Help, (2026),
https://www.nativeassignmenthelp.co.uk/accounting-for-business-individual-report-53115
Native Assignment Help (2026) [Online]. Retrieved from:
https://www.nativeassignmenthelp.co.uk/accounting-for-business-individual-report-53115
Native Assignment Help. (Native Assignment Help, 2026)
https://www.nativeassignmenthelp.co.uk/accounting-for-business-individual-report-53115
- FreeDownload - 40 TimesEffective Marketing Communication Plan For Apple's iPhone 15 Launch Assignment Sample
Effective Marketing Communication Plan For Apple's iPhone 15...View or download
- FreeDownload - 39 TimesBSS057-6 Corporate Innovation And Entrepreneurship Assignment Example
Introduction - BSS057-6 Corporate Innovation And Entrepreneurship The...View or download
- FreeDownload - 46 TimesBanking and Finance Assignment Sample
Banking and Finance Assignment Sample A. Explain and justify the stage...View or download
- FreeDownload - 41 TimesDocumentary Analysis With Descriptive Annotated Bibliography Assignment Sample
Documentary Analysis With Descriptive Annotated Bibliography Introduction...View or download
- FreeDownload - 43 TimesUnit3: Safeguarding Children and Young People - Assignment Sample
Unit 3: Understand How to Support Children and Young People MAIN BODY 1.1 The...View or download
- FreeDownload - 43 TimesUnit 7 Business Law Assignment Sample
Unit 7 Business Law Assignment Task 1 (LO1) Introduction - Unit 7 Business...View or download
-
100% Confidential
Your personal details and order information are kept completely private with our strict confidentiality policy.
-
On-Time Delivery
Receive your assignment exactly within the promised deadline—no delays, ever.
-
Native British Writers
Get your work crafted by highly-skilled native UK writers with strong academic expertise.
-
A+ Quality Assignments
We deliver top-notch, well-researched, and perfectly structured assignments to help you secure the highest grades.